
Payment Processing for Vacation Rentals: Fees, Options and Security
Quick Summary
Payment processing for vacation rentals is the system that takes a guest's money through a card network and into your bank account. Its costs include card fees, currency conversion, refund and chargeback charges, and VAT, so compare providers on the all-in cost.
Check whether your processor charges fees when a booking is refunded or disputed.
Use the same worked example in GBP to compare every provider's all-in cost.
Ask how the provider handles Strong Customer Authentication to avoid extra declines.
Keep VAT invoices from each provider so the figures are recoverable at year end.
Take a deposit at booking and collect the balance before arrival.
Are your payment fees higher than they should be?
Switch4Profit reviews your statements and contracts at no cost.
Table of Contents
How Payment Processing Works for Vacation Rentals
Last Updated: 7 November 2026
Payment processing for vacation rentals is the system that takes a guest's money, moves it through a card network, and lands it in your bank account.
When a guest pays, the card details go to a payment gateway, which checks the card and asks the bank to approve the amount.
A payment processor connects these parts. Whichever model you choose, keeping payments and booking decisions manageable from a distance is part of the same operational picture, as King's Choice Solutions shows.
Holiday rentals add complications a shop or café doesn't face.
Watch out: Check whether your processor charges when a booking is refunded or disputed, not only when it is first paid.
Accepted Payment Methods and Booking Workflows
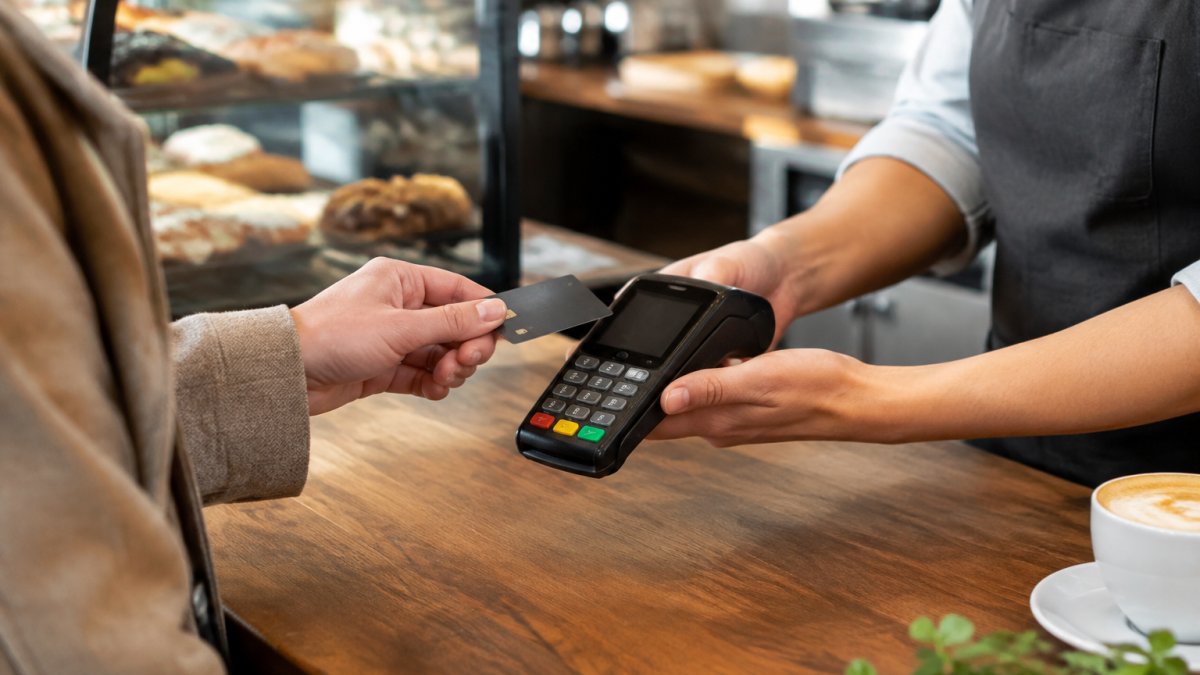
Many vacation rental operators accept debit and credit cards, and some also accept digital wallets such as Apple Pay and Google Pay. Bank transfers can suit some longer lets and corporate bookings, though they are slower to confirm.
The booking workflow matters as much as the payment methods. A typical sequence runs like this:
The guest reserves the property and pays a deposit or the full amount.
The system sends a confirmation and records the payment.
A balance is collected before arrival, if your terms require it.
The payout is released to you after the stay or on a set schedule.
Gaps in this sequence cause the most admin. If your booking software doesn't talk to your payment provider, someone has to reconcile the two by hand each month.
Holiday Rental Payment Fees: What You Actually Pay
Fees are where most owners lose money without noticing. The headline rate is rarely the whole cost: card processing, currency conversion, platform commission, refund fees and payout charges can all appear on different statement lines, and some are quoted exclusive of VAT while others are inclusive, making like-for-like comparison harder than it looks.
The advertised percentage can look reasonable while the total cost per booking turns out higher once every charge is added up. Rather than relying on a sales brochure, take one month of real transactions and calculate the full cost against each quote.
The charges that make up your total cost
When you assess a provider, work through every line below. Ask for each in writing, and confirm whether the figure includes VAT at 20%.
Card processing: a percentage plus, often, a fixed pence amount per transaction. Debit and credit cards can be priced differently, and commercial or premium cards frequently cost more than the headline consumer rate.
Digital wallet charges: Apple Pay and Google Pay are usually priced like card payments, but confirm rather than assume.
Currency conversion: if a guest pays in euros or dollars, the processor converts to GBP. The margin is often buried in the exchange rate rather than shown separately, so ask what markup applies over the interbank rate.
Refund fees: some providers return the original processing fee, some retain it, and some charge an additional refund fee. Over a season with several cancellations, this adds up.
VAT and your records
Most payment processing services are subject to VAT at the standard rate, and a VAT-registered operator can usually reclaim the VAT on business charges. If you are not VAT-registered, the gross cost hits your margin. Keep VAT invoices from each provider so the figures are recoverable and your bookkeeping reconciles at year end. If you are close to the VAT registration threshold, model how processing fees and any platform commission affect your turnover before you cross it.
A like-for-like comparison method
To compare providers fairly, use identical inputs for each. Take a typical booking value, a typical number of bookings per month, and the share of guests paying by card versus wallet versus bank transfer. Then apply the same calculation to every quote:
Multiply the per-transaction percentage by the booking value.
Add the fixed pence charge per transaction.
Add any monthly, gateway or PCI fee, divided by the number of bookings.
Add expected refund and chargeback costs based on your actual cancellation rate.
Add any payout or currency-conversion charge.
Add VAT where it applies and you cannot reclaim it.
Applying the same calculation to every quote shows which provider is cheapest for your actual booking pattern.
Watch out: A quote that looks cheapest on the headline percentage can be the most expensive once refund fees, currency margin and VAT are included, so ask for the all-in cost on a worked example in GBP.
The charges that make up your total cost are easy to miss on a statement, so it helps to check each one against your quote.
Charge | What it covers | What to check |
Card processing | Percentage plus, often, a fixed pence amount per transaction | Debit and credit cards may be priced differently |
Currency conversion | Margin on non-GBP payments | Ask what markup applies over the interbank rate |
Refund fees | Returning or retaining the original processing fee | Some providers charge an extra refund fee |
Chargeback fees | Fixed amount per dispute | Check whether it is refunded if you win |
Payout fees | Faster or non-GBP settlement | Standard UK settlement is often free |
Monthly, gateway or PCI fees | Account, gateway or non-compliance charges | Confirm PCI DSS status |
Direct Booking Payment Systems Compared
Direct bookings, where guests book through your own website rather than a marketplace, avoid platform commission but place the payment workload on you.

Systems differ in how they handle these tasks. Some are built into property management software, keeping bookings and payments in one place; others are standalone gateways that need manual linking.
Whichever route you choose, check that the system supports the deposit and refund steps you actually use.
Guest Deposit and Refund Management
Deposits protect you against late cancellations and damage. Most owners take a booking deposit at reservation and collect the balance closer to arrival.
Refunds need the same care. Set a clear cancellation policy, show it at checkout, and make sure your payment system can process partial refunds quickly.
Keep a record of every deposit, balance and refund against the booking.
Payment Security for Holiday Rentals
Security is not optional when you handle card data. Card details are best handled by a PCI DSS-compliant payment provider rather than collected by email, in spreadsheets or over the phone. If you do take card details manually, you are responsible for how they are captured, stored and destroyed, and that responsibility sits with you, not the processor.
Strong Customer Authentication
Strong Customer Authentication (SCA) is a requirement under the UK's implementation of the second Payment Services Directive, applying to most card payments where both payer and payee are in the UK or wider European Economic Area.
For holiday rentals this matters at the point of payment. A guest paying a deposit from a phone will usually see a bank authentication step, a push notification, in-app approval or one-time code.
Fraud screening and card verification
Card verification and fraud screening reduce the risk of accepting a stolen card. Common mechanisms include:
Address Verification Service (AVS) checks, which compare the billing address the guest supplies with the card issuer's records.
Card Verification Value (CVV) checks, which confirm the security code on the card.
3-D Secure authentication, which routes the guest through their bank's SCA step.
Velocity and risk rules, which flag unusual patterns such as multiple bookings from one card or a booking made from a country that does not match the guest's stated location.
No single check is conclusive. A booking can pass every automated check and still be fraudulent, so keep records of the guest's communication, the booking terms they accepted and the identity details you collected, your evidence if a chargeback arrives months later.
Data protection responsibilities
Guest data also needs protecting. Under the UK GDPR and the Data Protection Act 2018, you are generally a data controller for the personal information you collect about guests, and your payment provider is usually a processor acting on your instructions.
In practice this means:
Give guests a clear privacy notice explaining what payment data you collect and why.
Keep only the data you need, and delete card details once they are no longer required.
Have a written agreement with each processor covering how they handle data on your behalf.
Know how you would respond to a data breach, including when you would need to notify the Information Commissioner's Office.
The Information Commissioner's Office publishes guidance for businesses on these points, and it is worth reading before you change providers rather than after.
Practical checks before you sign
Look for these features when assessing a provider:
Card verification and fraud screening on each transaction, with the ability to set your own risk rules.
Encrypted checkout pages and tokenisation, so card details are not stored on your own systems.
Two-factor authentication for your own dashboard, because account takeover is a real risk for small operators.
Clear reporting so you can spot unusual activity quickly and export records if you switch.
Security is not a one-off setup task. Review your provider's controls annually, check that staff who take payments know the rules, and confirm that any booking software you connect has not introduced a weaker link in the chain.
Chargebacks, Payouts and Switching Processors Without Losing Money
A chargeback happens when a guest disputes a payment with their card issuer.
Payout timing is the other cash flow issue. Some providers pay out daily, others weekly or after the stay.
If you switch processors, plan carefully. Confirm what exit fees your current contract allows, when the old account will close, and how held funds or future bookings will be transferred.
Ask each new provider how much help they give with the switch itself.
Booking Your Free Business Cost Review
If you want to see what your current payment setup really costs, Switch4Profit offers a free business cost review. The review looks at your statements and contract terms, and sets out where fees may be reduced.
You can also see Dojo card terminal options, with free installation, staff training and ongoing support, through our Taking Payments page. To learn more about who runs the review and what it involves, read about the free business cost review before you book.
GET MY FREE BUSINESS COST REVIEW
Frequently Asked Questions
How do holiday rental payment processors work?
A payment processor takes a guest's card details, asks the card issuer to authorise the amount, and then settles the funds into your bank account, usually after a short delay. For holiday lets the processor often also handles deposits held as authorisations, split payments between owners and managers, and refunds. Check whether the processor is a specialist for short-term rentals, how payouts are timed, and whether it integrates with your booking software, because these details decide how much manual work you will do each week.
How much do payment processors charge holiday rental businesses?
Fees vary by processor, card type, transaction volume and whether you pay per transaction or through a monthly plan, so there is no single standard figure to quote. Compare providers on total cost for a typical month of bookings, including card fees, currency conversion, payout charges, refund fees and any monthly minimums. Ask each provider for a written breakdown in pounds sterling so you can compare like with like before you commit.
Can I take direct bookings and payments for a holiday let?
Yes. Many owners take direct bookings through their own website or booking link and collect payment through a processor connected to that channel, which avoids some platform commission. You will still need to set clear cancellation terms, collect a deposit or full payment securely, and keep records for your accounts. Check that your chosen system can send payment links, hold deposits and reconcile payments with your accounting software.
Which payment methods should a holiday rental business accept?
Most owners accept major debit and credit cards, which guests expect and which cover most bookings. Adding digital wallets such as Apple Pay and Google Pay can speed up checkout on mobile, and bank transfer suits longer stays or guests who prefer it. Offering several options usually reduces abandoned bookings, but each method carries its own fees and settlement timing, so weigh those costs before enabling them.
Comments